What is the scope and industry significance of the Diode-Pumped Solid State (DPSS) Lasers Market?
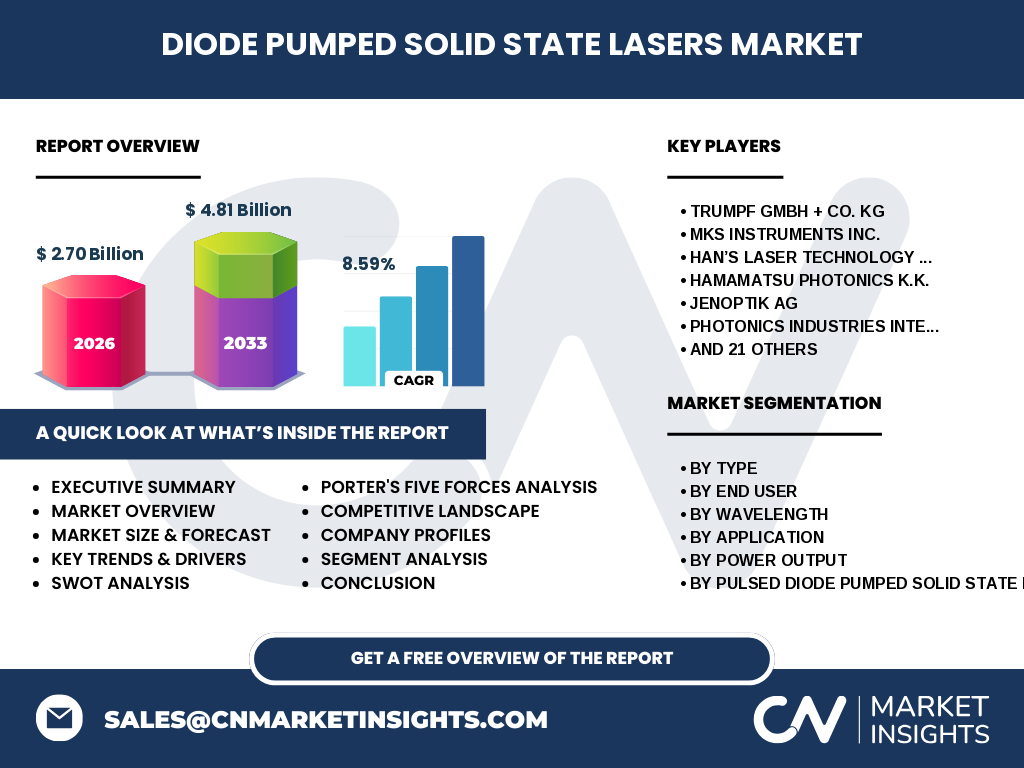
Our analysis indicates that the Diode-Pumped Solid State (DPSS) Lasers Market anchors high-precision manufacturing, biomedical instrumentation, and defense targeting. Valued at $2.70 Billion in 2026, these lasers replace traditional lamp-pumped systems by utilizing semiconductor laser diodes to pump a solid gain medium, offering superior beam quality and thermal management essential for micro-machining.
What are the primary market drivers, restraints, challenges, and opportunities shaping the Diode-Pumped Solid State (DPSS) Lasers Market?
Structural growth stems from escalating demand for ultra-short pulse widths in semiconductor fabrication. Conversely, strict compliance mandates from the FDA and CDRH regarding laser safety restrict deployment speeds. Supply chain vulnerabilities surrounding rare-earth crystal growth pose manufacturing bottlenecks, though expanding adoption in additive manufacturing unveils lucrative avenues.
Emerging trends and growth patterns in the Diode-Pumped Solid State (DPSS) Lasers Market
The market is witnessing a profound shift toward miniaturized air-cooled continuous wave lasers and high-power ultraviolet variants. Industry leaders like Coherent Corp. and Trumpf GmbH + Co. KG are integrating IoT-enabled diagnostics directly into industrial workstations, driving predictive maintenance and higher uptime across automotive lines.
How did COVID-19 impact the Diode-Pumped Solid State (DPSS) Lasers Market and what is its recovery trajectory?
The pandemic severely disrupted optoelectronic component logistics originating from East Asian manufacturing hubs. However, accelerated automation investments in electronics assembly fueled a robust V-shaped recovery, positioning the market to expand toward $4.81 Billion by 2033 at a steady 8.59% CAGR.
Competitive benchmarking and strategic dynamics in the Diode-Pumped Solid State (DPSS) Lasers Market
Market concentration remains moderately high, characterized by aggressive vertical integration among tier-one players such as MKS Instruments Inc. and Hamamatsu Photonics K.K. Smaller specialists like Skylark Lasers Ltd. compete by targeting ultra-low noise niches, forcing major conglomerates to pursue targeted mergers to capture specialized optical intellectual property.
Executive summary of key findings for the Diode-Pumped Solid State (DPSS) Lasers Market
Driven by a robust 8.59% CAGR from 2027 to 2033, the Diode-Pumped Solid State (DPSS) Lasers Market industry trends highlight a transition from macro-processing to nano-scale precision. Total valuation is projected to surge from $2.70 Billion in 2026 to $4.81 Billion by 2033, heavily catalyzed by advancements in ultrafast picosecond and femtosecond architectures.
Market forecast trajectory from 2027 to 2033
Based on our econometric modeling, the market will scale aggressively from its 2026 baseline of $2.70 Billion to achieve $4.81 Billion by 2033. This expansion is underpinned by a consistent 8.59% CAGR, fueled by burgeoning demand for ultraviolet micromachining and quantum technology research platforms.
Comprehensive segmentation analysis of the Diode-Pumped Solid State (DPSS) Lasers Market
Segmentation spans multiple dimensions: By Type (Continuous Wave and Pulsed); By End User (Manufacturing, Healthcare, Defense, Research Institutions); By Wavelength (Green, Red, Infrared, Ultraviolet); By Application (Industrial, Medical, Scientific, Defense, Optical Communication, Micromachining, Display); By Power Output (Low, Medium, High); alongside specialized sub-segments for pulsed and continuous-wave configurations.
Geographic distribution and regional performance in the Diode-Pumped Solid State (DPSS) Lasers Market
Geographic performance is led by Asia-Pacific, propelled by heavy electronics manufacturing clusters in Shenzhen and Seoul. Meanwhile, North America captures high-value market share through defense contracts and advanced biomedical research facilities, supported by key regional innovators like RPMC Lasers Inc. and Power Technology Inc.
In-depth regional review of high-growth manufacturing hubs
In Europe, strict adherence to IEC 60825-1 safety standards dictates optical engineering practices, favoring precision-focused manufacturers like Jenoptik AG and TOPTICA Photonics AG. Simultaneously, North American regional demand thrives on aerospace micro-drilling requirements, heavily engaging suppliers situated near major cargo transport hubs.
Company profiles and strategic positioning of leading market participants
Industry stalwarts such as Han’s Laser Technology Industry Group Co. Ltd. leverage economies of scale for mass industrial deployment. Conversely, specialty firms like Ekspla UAB and Litron Lasers Ltd. dominate scientific research applications by engineering high-energy, narrow-linewidth pulsed systems tailored for academic laboratories.
Porter's Five Forces analysis of competitive intensity
The threat of new entrants remains constrained by high capital expenditure requirements for cleanroom optical assembly and proprietary crystal growth IP. However, intense rivalry among established giants such as Coherent Corp. and Trumpf GmbH + Co. KG exerts continuous downward pressure on industrial laser margins.
SWOT analysis of the Diode-Pumped Solid State (DPSS) Lasers Market
Strengths include exceptional beam pointing stability and energy efficiency. Weaknesses involve complex thermal management needs in high-power configurations. Opportunities lie in quantum computing optical interfaces, while external threats stem from semiconductor supply chain disruptions and geopolitical trade restrictions on optical-grade crystals.
Value chain analysis from raw materials to end-users
The value chain initiates with the synthesis of synthetic gain crystals (e.g., Nd:YAG) and high-power semiconductor laser diodes. Mid-stream integrators assemble these into sophisticated resonators, which are ultimately distributed to end-users in automotive, medical, and defense sectors via specialized value-added distributors.
Strategic investment insights and high-potential areas
Investors should direct capital toward ultraviolet and femtosecond pulsed DPSS technologies, as these segments experience the highest pricing power. Companies possessing proprietary intra-cavity harmonic generation capabilities represent prime acquisition targets for major conglomerates seeking technological differentiation.
Conclusion and core takeaways for market stakeholders
The Diode-Pumped Solid State (DPSS) Lasers Market analysis proves that technological convergence between semiconductor efficiency and solid-state reliability is non-negotiable for future industrial competitiveness. Reaching $4.81 Billion by 2033, success will favor firms that master thermal management and ultra-short pulse delivery.
Research methodology underpinning the market sizing and forecast
Our baseline estimates are triangulated using a robust mix of secondary customs trade registries, primary qualitative interviews with Chief Technology Officers across AMS Technologies AG, Lumibird, and NKT Photonics, and cross-correlation with macroeconomic industrial output indexes.
Scope of the report, coverage parameters, and operational limitations
This report covers global revenue estimations from 2026 to 2033, analyzing all major technological configurations, wavelengths, and end-user verticals. Excluded from this scope are low-purity commercial diode lasers lacking solid-state crystal integration and unverified gray-market optical components.
Recent developments, corporate announcements, and strategic alliances
Recent market dynamism features strategic joint ventures aimed at scaling quantum communication hardware. Notable moves by Amplitude Laser and MKS Instruments Inc. highlight an industry-wide push to acquire ultrafast laser patents and expand European production footprints.